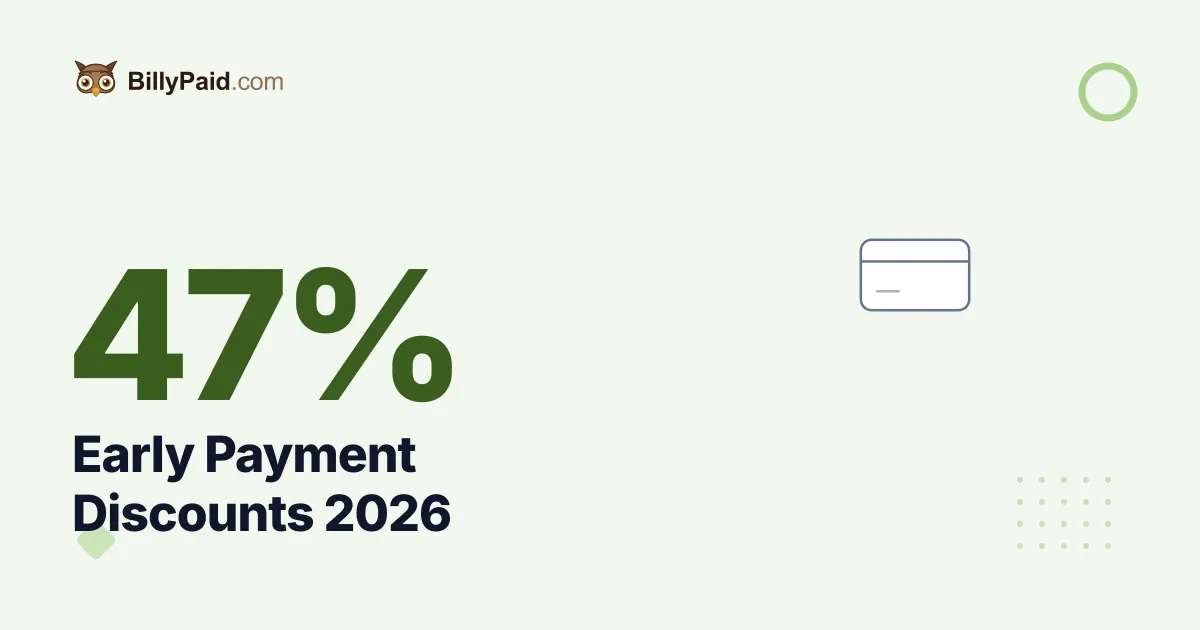
47% of businesses have received an early payment discount from a supplier in the past 12 months, according to a PYMNTS and Airbase survey of 225 accounts payable executives. Yet only 24% of the businesses offered a discount take it every single time it’s available. That gap between “offered” and “always captured” is the entire story of this post: a 2% discount for paying 20 days early is worth an annualized 36.7% return, and most businesses that get the offer still leave part of it on the table.
Figure 1: Nearly half of all businesses have been offered an early payment discount by a supplier in the past year. Source: PYMNTS/Airbase, “Improving Financial Performance: Taking Advantage Of Early Payment Discounts,” 2022.
What percentage of businesses actually get offered an early payment discount?
Just under half. PYMNTS and Airbase surveyed 225 accounts payable executives at SaaS companies with 100 to 1,500 employees in mid-2022 and found that 47% had received an early payment discount from at least one supplier in the previous 12 months. The offer wasn’t evenly distributed by company size: 56% of larger firms in the sample said they’d been offered a discount, compared to 39% of smaller firms, a 17-point gap that tracks with how much negotiating leverage a buyer typically has with its suppliers. Discount size varied too: 26% of firms that received a discount reported it was worth up to 10% of the payment obligation, and 21% said their discount exceeded 10%, though the most common structure by far, across the wider trade-credit literature, is a modest 1-2% discount tied to a 10-day payment window on top of a 30-day term. The survey itself is scoped to SaaS accounts payable teams rather than small businesses broadly, so treat the exact 47% figure as directional for other B2B sectors rather than a universal constant, even though the underlying incentive to offer a discount doesn’t change by industry.
Figure 2: Larger firms are offered early payment discounts noticeably more often than smaller firms. Source: PYMNTS/Airbase, 2022.
How many businesses actually take the discount once it’s offered?
A minority, and that’s the real gap in this data. Of the businesses offered an early payment discount, only 24% said they took advantage of it every single time, per the PYMNTS/Airbase survey. Another 22% took it more than 75% of the time but not always, and a small 4.8% never used an available discount at all. That leaves close to half of the sample somewhere in the middle, taking the discount sometimes but not consistently. The gap isn’t about whether the discount is worth it; the math on that is settled and covered below. It’s about process: firms using a non-payroll spend management system captured a discount roughly two-thirds of the time, well above the 47% baseline, which points to timing and approval friction, not the size of the discount, as the more common reason it gets missed. A payment reminder workflow that flags invoices approaching their discount deadline closes that same gap on the receivables side, before a customer’s own AP bottleneck turns a discount offer into a missed one.
Figure 3: Only a minority of businesses take an available early payment discount every time it’s offered. Source: PYMNTS/Airbase, 2022.
What is a 2/10 net 30 discount actually worth in annual terms?
More than most business owners assume. The most common early payment discount structure is 2/10 net 30: a 2% discount for paying within 10 days, against a full 30-day term. Skipping that discount to hold onto cash for 20 extra days is mathematically equivalent to paying an annualized rate of 36.7% for the privilege, using the standard trade-credit formula: (discount% / (1 - discount%)) x (360 / (net days - discount days)), or (0.02 / 0.98) x (360 / 20) = 36.7%. Put another way, a business that consistently declines a 2/10 net 30 discount is turning down a better return than almost any short-term financing product would cost it to borrow the same cash instead, which is exactly the comparison the next chart makes explicit against real 2025 small business loan rates. That’s the calculation behind the net 30 vs net 7 payment data showing invoices with shorter stated terms get paid measurably faster: a real incentive attached to a real deadline changes behavior, whether that incentive is a shorter clock or a discount.
Figure 4: The annualized value of a standard 2/10 net 30 discount runs far above what a small business typically pays to borrow the same cash short-term. Source: calculated from the standard trade-credit discount formula; loan rate from Federal Reserve Bank of Kansas City Small Business Lending Survey, Q4 2025 report.
How does the annualized value change with different discount terms?
Substantially, and the discount percentage matters more than the payment window. A 1/10 net 30 discount, half the size of 2/10 net 30, is worth an annualized 18.2%, roughly half the return, since the discount percentage and the annualized rate move together almost linearly. Stretching the full term out to 45 days while keeping the same 2% discount, 2/10 net 45, drops the annualized value to 21%, because the buyer gets to hold the discount-free cash for a longer stretch before the comparison period even starts. A steeper 3% discount on the same 2/10 net 30 structure, 3/10 net 30, pushes the annualized value up to 55.7%. The pattern holds across every variation: a supplier trying to accelerate cash collection gets more behavioral pull from a bigger discount percentage than from a shorter payment window, because the percentage compounds into the annualized figure directly while the window only changes how many times a year that return effectively repeats.
Figure 5: A bigger discount percentage moves the annualized value more than a shorter payment window does. Values calculated from the standard trade-credit discount formula.
Is offering a discount actually better than just enforcing shorter payment terms?
They’re solving different problems, and the invoice payment terms data suggests most businesses need both levers, not one instead of the other. A discount rewards a customer who could pay sooner but has no other reason to; a firm due date with reminders backing it up pressures a customer who’s simply slow. The US B2B average payment term runs 46 days, per Atradius, and a 2/10 net 30 offer sitting inside that norm gives an early-paying customer a real reason to move faster than the market default without requiring a confrontation over an overdue balance. For customers who don’t respond to the discount, that’s exactly the group structured reminder cadences are built to handle: the two tools work on different segments of the same customer base, not as substitutes for each other.
| Discount term | Discount % | Days paid early | Annualized value |
|---|---|---|---|
| 1/10 Net 30 | 1% | 20 | 18.2% |
| 2/10 Net 45 | 2% | 35 | 21.0% |
| 2/10 Net 30 | 2% | 20 | 36.7% |
| 3/10 Net 30 | 3% | 20 | 55.7% |
Table 1: Annualized value by common discount term structure. A 2/10 net 30 discount, the most widely used structure, is worth 36.7% annualized. Source: calculated from the standard trade-credit discount formula.
| Metric | Share | Source |
|---|---|---|
| Businesses offered an early payment discount | 47% | PYMNTS/Airbase, 2022 |
| Always take the discount when offered | 24% | PYMNTS/Airbase, 2022 |
| Take it more than 75% of the time, not always | 22% | PYMNTS/Airbase, 2022 |
| Never take an available discount | 4.8% | PYMNTS/Airbase, 2022 |
Table 2: How often businesses capture an early payment discount once it’s on offer. Source: PYMNTS/Airbase, “Improving Financial Performance: Taking Advantage Of Early Payment Discounts,” 2022.
The Bottom Line
The math on early payment discounts isn’t close: a standard 2/10 net 30 offer is worth an annualized 36.7%, several times what a typical small business pays to borrow the same cash short-term. The gap this data actually exposes is operational, not financial. 47% of businesses get offered a discount, but barely a quarter capture it consistently, and the businesses running automated AP processes catch it at roughly double the rate of everyone else. The lesson runs in both directions for anyone running a business: on the payable side, a discount deadline is worth building a process around rather than hoping someone remembers it; on the receivable side, offering one costs a couple of points off the invoice total but converts a customer who was going to pay eventually into one with a concrete reason to pay sooner. A BillyPaid invoice can carry discount terms directly on the document, and a payment reminder sequence timed to the discount window does the remembering that the PYMNTS/Airbase data shows most businesses currently skip.
Frequently Asked Questions
What percentage of businesses offer or receive early payment discounts? 47% of businesses have received an early payment discount from a supplier in the past 12 months, according to a PYMNTS and Airbase survey of 225 accounts payable executives at SaaS companies (published November 2022). Larger firms (100+ employees) were offered discounts more often, 56% versus 39% for smaller firms in the same survey.
How much is a 2/10 net 30 discount actually worth? A 2/10 net 30 discount, 2% off for paying within 10 days instead of the full 30, works out to an annualized return of approximately 36.7% for the money used to pay early. That’s calculated as (discount% / (1 - discount%)) x (360 / (net days - discount days)): (0.02/0.98) x (360/20) = 36.7%.
Do most businesses actually take the discount when it’s offered? No. Among businesses offered an early payment discount, only 24% take it every single time, and 22% take it more than 75% of the time but not always, per the PYMNTS/Airbase survey. Businesses using automated accounts payable software captured discounts at roughly double the rate of the overall sample.
Is taking an early payment discount better than keeping the cash? For most small businesses, yes. The Federal Reserve Bank of Kansas City’s Small Business Lending Survey put fixed-rate small business term loans at roughly 7% in late 2025, well below the 36.7% annualized return of a standard 2/10 net 30 discount. Unless a business has no other source of short-term cash, forgoing the discount is usually the more expensive option.
Sources and References
- PYMNTS and Airbase: “Improving Financial Performance: Taking Advantage Of Early Payment Discounts” (survey of 225 accounts payable executives at SaaS companies, 100-1,500 employees, fielded May-June 2022, published November 7, 2022), share of firms offered and capturing early payment discounts, by company size and AP automation status.
- HighRadius: 2/10 Net 30 Early Payment Discount, Formula & Examples, worked annualized-return calculation for 2/10 net 30 discount terms.
- Federal Reserve Bank of Kansas City: Small Business Lending Survey (Q4 2025 report, covering Q3 2025 lending data), average fixed and variable-rate small business term loan rates by urban/rural bank.
- FreshBooks: Use Your Invoice Payment Terms to Get Paid Faster (analysis of 1.39M+ small business invoices), payment speed by stated invoice term length, cited for context on term-length incentives.
Note: All figures verified as of October 2026. The annualized discount-value figures in this post (36.7%, 18.2%, 21.0%, 55.7%) are calculated directly from the standard trade-credit discount formula, not survey-reported figures, and will not change with future data refreshes.